Holding Companies in Greece: Tax Advantages and When They Make Sense
1. Introduction: What a Holding Company Is and Why It Is a Strategic Tool
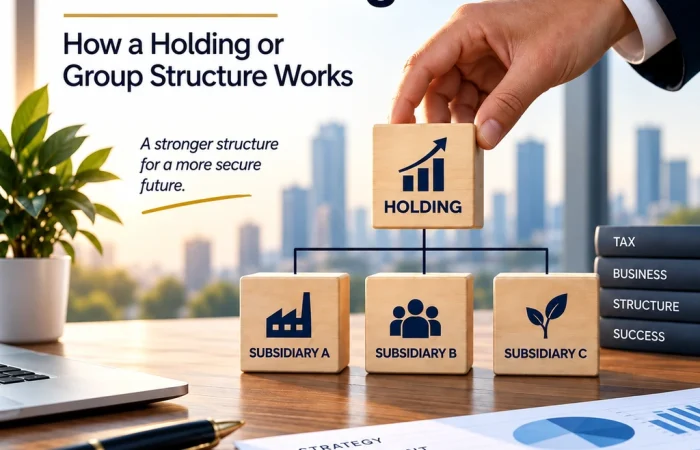
A holding company, or as rendered in Greek legal and economic terminology, a company of participations, is a legal entity whose main and often sole activity is the holding of shares, equity stakes or other participation titles in one or more subsidiary companies. In contrast to businesses that seek commercial profitability through production, sales or service provision, a holding does not carry out typical business activity in the traditional sense.
Its function is based on control, administrative oversight, management of participations, and financial monitoring of subsidiaries. This enables it to operate as a central corporate hub, unifying the operational, financial, and managerial activities of a group of companies.
The holding model is not new. Since the late 19th century, large business groups and trusts in the U.S. and Europe used similar structures to concentrate and control interests. In modern times, the concept of the holding is revived within a globalized context with aims of tax rationalization, legal security, facilitation of cross-border investments, and financial centralization in business groups.
For an individual investor, an entrepreneur with interests in multiple companies, a tax-sensitive group, or even a family wealth succession organization, the holding company is a strategic business engineering tool.
Especially in Greece, which since 2019 has directly incorporated the relevant EU directives and enacted structural tax reforms, the holding model constitutes a lawful, attractive, and operationally effective vehicle for the professional, the company, the investor, and the heir.
2. Legal and Institutional Definition of a Holding Company
The concept of a holding company, although not designated by this term in Greek legislation, is recognized by its function and classified among the so-called companies of participations.
2.1 Substantive and Formal Definition
Substantively, a company of participations is a legal entity that:
-
Does not engage in productive or commercial activity,
-
Exercises management or control over subsidiary companies, and
-
Earns income from participations, such as dividends, capital gains from the sale of shares, interest from loans to subsidiaries, etc.
Formally, the company may be established in any of the following forms:
-
Société Anonyme (S.A.),
-
Private Company (IKE),
-
Limited Liability Company (EPE) – although its use has declined,
-
Or even as a foreign company establishing a branch in Greece.
What matters is the purpose stated in its Articles of Association, which must include participation in other companies, management of participations, and business administration through participations.
2.2 Legislative Basis
The holding concept is recognized in Greek tax and commercial law through:
-
Article 48A of Law 4172/2013 (Income Tax Code): exemption of capital gains from the transfer of participation titles,
-
Article 48 paragraphs 3 and 4: exemption from dividend tax between associated companies within the EU,
-
Provisions of Law 4548/2018 on S.A.s (regarding participations and indirect management),
-
Law 3419/2005 (GEMI) and Law 4919/2022, where participation activities are recognized as legitimate economic activities (KAD).
2.3 Economic Activity Code (KAD)
The main KAD for holding companies is:
64.20.10.01 – Participation activities in enterprises (Holding)
Its use is crucial for the proper recognition of the activity by the tax administration and for the application of tax exemptions.
3. Holding Structures in Greece: Categories and Legal Forms
In practice, holding companies in Greece are organized using various structures, depending on the number of participations, the level of capital, the type of supervision exercised, and the international scope of activity.
3.1 Categories of Holdings by Function
i. Vertical Holdings
Hold participations in companies operating at different levels of function, e.g., production → distribution → sales. They supervise each stage of the production chain.
ii. Horizontal Holdings
Hold participations in similar or complementary companies with shared objectives or products, often for market control or cost unification.
iii. Financial Holdings
Do not exercise any management but handle financial outcomes from participations (e.g., dividends, interest, valuations).
iv. Intermediate Holdings
Act as intermediaries between foreign parent companies and Greek subsidiaries for participation, capital transfer, or control purposes.
3.2 Choice of Legal Form
The most common forms for establishing a holding in Greece are:
-
Société Anonyme (S.A.): Preferred when there is a need to attract investors, for international structure, prestige, publicity, and the ability to appoint a Board of Directors.
-
Private Company (IKE): Chosen for flexibility, low incorporation cost, simplified procedures, and no requirement for a notary.
-
Foreign Holdings (e.g., Luxembourg, Cyprus, Netherlands B.V.): Sometimes used as parent holdings that establish branches or subsidiaries in Greece for tax planning within the EU framework.
4. Tax Advantages of Holding Companies in Greece
The Greek tax system, following the structural changes introduced by Law 4172/2013 (Income Tax Code) and especially its amendment by Law 4646/2019, is now aligned with EU principles and offers a tax-neutral and operationally competitive framework for the establishment and operation of holding companies.
A holding company in Greece may benefit from the following:
-
Exemption from capital gains tax on transfer of participations (Article 48A),
-
Exemption from dividend tax on distributions from subsidiaries (Article 48(3) & (4)),
-
Exemption from capital accumulation tax,
-
Ability to offset losses from participations,
-
Preservation of legal liability separation and asset ring-fencing.
Greece’s approach in recent years has been to make the country investment-friendly for participation structures — and notably without extreme tax privileges that would risk classification as a “tax haven.” The regime is consistent, secure, and applicable under clear conditions.
5. Capital Gains Tax Exemption
5.1 What Is Capital Gain
Capital gain is the difference between the sale price of shares or equity interests and their acquisition price. In the past (until 2014), such gains for legal entities were not taxed at all. From the enactment of Law 4172/2013, taxation was imposed, but with the introduction of Article 48A, conditions were established for full exemption.
5.2 Exemption under Article 48A of Law 4172/2013
Article 48A was introduced by Law 4646/2019 and provides that:
“Income earned by a legal person or entity that is a tax resident of Greece, from the transfer of participation titles, is exempt from income tax, provided that:
(a) the transferring company holds at least 10% of the capital of the transferred company,
(b) the holding period was at least 24 continuous months before the transfer.”
5.3 Conditions for Application
For exemption from capital gains tax:
-
The company transferring the participation titles must be a tax resident of Greece.
-
It must hold at least 10% of the titles for a continuous period of 24 months.
-
Titles may include shares, IKE equity interests, EPE company shares, or other participation titles in domestic or EU legal entities.
-
Stock market listing is not required.
5.4 Key Points
-
No capital gains tax is imposed.
-
No stamp duty or capital accumulation tax is imposed.
-
It does not affect the holding’s status regarding other income (e.g., interest or dividends).
5.5 Strategic Advantage
The ability of a holding company to sell its participation without tax cost is a strategic advantage, particularly for investment funds, family wealth management structures, or companies planning capital reinvestment.
6. Dividend Tax Exemption
6.1 The General Framework
According to Article 48 paragraphs 3 and 4 of Law 4172/2013, dividends distributed from one legal entity to another, which are both tax residents of Greece or the EU, can be partially or fully exempt from tax, subject to conditions.
This provision incorporates the EU Parent-Subsidiary Directive (Directive 2011/96/EU).
6.2 Conditions for Exemption
The exemption applies when:
-
The parent (the holding) holds at least 10% of the participation titles of the subsidiary.
-
The holding period is continuous for at least 24 months.
-
Both legal entities are tax residents of Greece or another EU Member State.
6.3 What Is Exempted
-
The dividend received by the parent is not included in taxable profits.
-
No 5% dividend withholding tax applies (which is imposed on distributions to individuals).
-
There is full tax neutrality in dividend movement within the group.
6.4 Advantages
-
The holding company can receive dividends from subsidiaries without tax burden and reinvest or allocate them to other subsidiaries.
-
Double taxation of group profits is avoided.
-
It provides a tax incentive for organizing subsidiaries through a central holding.
7. Exemption from Capital Accumulation Tax and Other Reliefs
7.1 What Is the Capital Accumulation Tax
The capital accumulation tax is a levy previously imposed on share capital increases of legal entities. Under the old regime, capital injections (e.g., cash contributions, reserve capitalizations) were subject to a 1% tax on the contributed amount.
7.2 Abolition or Exemption for Holdings
Since January 1, 2020, with amendments to the corporate tax regime, the capital accumulation tax no longer applies when:
-
The share capital increase is intended for investment in other companies (e.g., acquisition of equity interests),
-
The increase is carried out in line with the corporate purpose of the holding (e.g., management of subsidiaries).
The same applies to contributions used for acquiring shares in other companies, without bypassing the tax base.
As a result, a holding that performs capital increases to finance participations in other companies is no longer burdened by the additional 1% cost, increasing capital flow efficiency and reducing setup or expansion expenses.
8. Savings via Intragroup Transactions and Loss Transfers
8.1 The Role of Intragroup Transactions (Transfer Pricing)
The holding, when operating as a parent entity, can structure intragroup relationships with its subsidiaries, such as:
-
Loans between group companies (intragroup lending),
-
Provision of management, support, administrative, accounting, or compliance services,
-
Centralized purchasing and procurement to achieve economies of scale.
These transactions are subject to documentation review under Article 50 of Law 4172/2013, but they offer:
-
Tax flexibility, as part of the cost can be shifted internally,
-
Internal efficiency, via pricing of intragroup charges aimed at profit centralization,
-
Controlled cash flow within the group without the need for dividend distributions.
8.2 Loss Transfer (Tax Offset)
The holding, as the sole owner of subsidiaries, may utilize:
-
Tax loss transfer: If one subsidiary records profits and another losses, the holding cannot directly offset losses between subsidiaries, but it can concentrate profitability in a loss-making subsidiary through appropriate internal charging (e.g., service fees, royalties).
This enables smoother tax burdens at the group level.
9. Legal Conditions for Applying Tax Exemptions
All the aforementioned benefits are not automatic. The holding company must meet specific formal and substantive conditions, which are proven through statutory documents, balance sheets, and filings with the Independent Authority for Public Revenue (AADE).
9.1 Conditions for Capital Gains Exemption (Article 48A)
-
Continuous ownership of ≥10% of participation for at least 24 months before transfer.
-
Participation in a company that is a tax resident of Greece or the EU/EEA.
-
Recognized legal form of participation (e.g., S.A., IKE, EPE, or foreign entities with a comparable legal structure).
9.2 Conditions for Dividend Exemption (Article 48(3) & (4))
-
Continuous ownership of ≥10% of capital for 24 months.
-
Similar or compatible legal form between parent and subsidiary.
-
Evidence that the holding is not a mere conduit or shell company for tax avoidance.
-
Proof of substantial economic activity by the holding (e.g., real offices, staff, transactions, expenses).
9.3 Advisory Notes
-
Exemptions do not apply if the holding is artificially set up for tax avoidance (abuse of rights).
-
The tax authority may require documentation of real economic substance, especially in audit cases.
-
It is advisable to maintain detailed articles of association, agreements, invoices, and documentation.
10. Insurance, Audit, and Accounting Obligations
Although holding companies may not engage in traditional commercial activity, they are fully subject to the regulatory obligations imposed on all capital companies, depending on their form.
10.1 Insurance Obligations
10.1.1 IKE Manager
-
Mandatory insurance with EFKA as self-employed (Article 38, Law 4387/2016), regardless of remuneration.
-
Minimum contribution required even if the company has no revenue.
10.1.2 Board Members of S.A.
-
No remuneration or <3% shareholding: No insurance obligation.
-
With board remuneration and ≥3% shareholding: Insured as self-employed with EFKA.
-
With salary from employment contract and <3% shareholding: Insured as employees.
Thus, the choice of legal form (IKE or S.A.) and the compensation of management members have significant insurance implications, which must be assessed based on cost/benefit.
10.2 Audit Obligations
Holding companies are not exempt from mandatory audit if they meet the thresholds provided by:
-
Law 4308/2014 (Greek Accounting Standards),
-
Law 4449/2017 for mandatory audit of public interest entities.
Mandatory audit criteria:
-
Turnover over €1,500,000,
-
Assets over €2,500,000,
-
Staff over 50 employees.
A holding not meeting these thresholds may not be mandatorily audited, but if it owns subsidiaries that are, it is required to prepare consolidated statements if it holds more than 50% control.
10.3 Accounting Obligations
-
Mandatory use of double-entry accounting (regardless of turnover).
-
Preparation of balance sheet, income statement, and notes.
-
Submission of records to AADE via myDATA platform.
-
Retention of all documentation for any kind of intragroup transaction.
Having an organized cost accounting plan, internal pricing, and annual audits serves as a compliance safeguard and protects against fines.
11. Holding and Corporate Governance: Management, Structure, Flexibility
One of the greatest values of a holding company is its ability to provide structure and flexibility in the governance of a multi-company group.
11.1 Centralized Control
The holding controls its subsidiaries both through the articles of association and shareholding, either as:
-
100% parent (full control), or
-
Minority investor with statutory provisions.
This enables:
-
Centralized decision-making,
-
Group-wide strategy definition,
-
Unified management and financial policy.
11.2 Flexibility in Changes
The holding can change its shareholding structure, introduce new shareholders, absorb or merge subsidiaries without affecting each one operationally, since each subsidiary is a distinct legal entity.
11.3 Separation of Ownership – Management
The shareholders of the holding do not need to be directly involved in managing the subsidiaries.
They can appoint different management teams for each company — e.g., for real estate, commerce, technology.
This promotes a “corporate umbrella” model, with unified principles and specialized management teams.
12. Holding and Asset Protection
One of the least understood but most important advantages of a holding company is asset protection through legal layering.
12.1 Risk Isolation
The holding is not liable for the debts of its subsidiaries, nor are subsidiaries liable for the obligations of the holding. This means:
-
If a subsidiary goes bankrupt, the assets of other companies remain untouched.
-
The parent can limit its loss to the book value of the participation.
-
No subsidiary can extend risk to other group entities.
12.2 Avoiding Seizure / Bank Linkage
In case of litigation or enforcement against a subsidiary:
-
The holding’s bank accounts are not seized.
-
Participation titles remain in its ownership, unless abuse is proven (e.g., artificial structure).
12.3 Retaining Property or Participations as a “Fortress”
The holding can retain real estate, shares, trademarks, or patents, which it leases or licenses to other companies.
This way, key assets are not exposed to the business risk of operational subsidiaries.
13. Holding as a Tool for Wealth Transfer and Succession Planning
The holding is widely used as a vehicle for wealth transfer and business participation succession.
13.1 Consolidation of Assets in Corporate Form
An entrepreneur can transfer real estate, shares, or equity interests to a holding company.
Then, transfer the shares of the holding to heirs or investors.
This avoids fragmentation of assets.
13.2 Controlled Succession – Without Asset Splitting
The holding allows the creation of a structured plan for transferring wealth to the next generation, using quotas and specific provisions.
Through clauses in the articles of association, continuity of management can be ensured, and disputes prevented.
13.3 Zero or Low Transfer Tax
Shares of unlisted companies can be transferred with low taxation (depending on value).
Exemptions or reduced rates apply for inheritance or donation transfers, provided kinship conditions are met.
14. Holding and International Strategy: EU, EEA, Third Countries
A Greek holding company can operate in the international business environment either as:
-
A parent company with subsidiaries in the EU or beyond, or
-
A subsidiary of a foreign parent investing in Greece.
14.1 Participation in Intra-EU Group
Through EU directives, Greece offers a compatible and harmonized framework for operating intra-EU corporate groups:
-
Parent-Subsidiary Directive: tax exemption on distributed dividends and capital gains,
-
Interest and Royalties Directive: ability to pay interest and royalties without withholding, provided requirements are met,
-
VAT & VIES registration system: facilitates intra-community transactions.
14.2 Use for Investments in Third Countries
A Greek holding can be used by investors for:
-
Investments in Balkan countries,
-
Participations in European companies to access the EU,
-
Acting as an intermediary vehicle in multinational transactions (hub structure).
Advantages:
-
Favorable bilateral double taxation agreements,
-
Ability to record intragroup invoicing with no restrictions,
-
Reliable tax residency (OECD & EU member, not on FATF blacklist).
15. Practical Examples of Using Holding Companies
15.1 Family Business with 3 Activities
An entrepreneur owns:
-
A sole proprietorship in real estate,
-
A stake in a food company,
-
A tech startup with investors.
Solution:
He creates an S.A. holding company, which acquires the participations and takes on:
-
Issuance of consolidated balance sheets,
-
Receipt and distribution of dividends,
-
Assignment of management per activity.
Benefits:
-
Zero taxation on profit distribution between subsidiaries and parent,
-
Legal separation of liabilities and investments,
-
Future sale of only the startup (via sale of subsidiary participation).
15.2 Real Estate Investor with Portfolio of 5 Apartments
The investor rents the properties via Airbnb and long-term leases.
Solution:
Formation of a Single-Member IKE Holding, which:
-
Records the properties as assets,
-
Signs contracts with managers/platforms,
-
Reinvests profits without distributing to individuals.
Benefits:
-
Depreciation of purchase and improvement costs,
-
Smoothed tax burden,
-
Potential sale via transfer of company shares (not real estate).
16. Holding and Real Estate: Ownership and Exploitation
Using a holding company in real estate is common, especially for medium- to long-term return investments.
16.1 Ownership via Subsidiaries
A holding can:
-
Hold real estate directly on its balance sheet (ownership), or
-
Establish subsidiaries for each property, ensuring legal separation of investments.
Example: A portfolio of 5 properties is separated into 5 IKE subsidiaries, each owning one. The parent holding consolidates them.
16.2 Exploitation: Short-Term / Long-Term Leasing
The holding can:
-
Lease properties to third parties via rental or management agreements,
-
Manage through a dedicated operating subsidiary to separate income from property value.
16.3 Advantages
-
Investment depreciation via maintenance, interest, and improvements,
-
Zero capital gains tax upon transfer of company shares,
-
Structured taxation and possible ENFIA exemption under special regimes.
17. Holding and Startups – Investment Vehicles & Venture Capital
The holding is a key tool in modern startups and venture capital structures.
17.1 Participation in Startups
An investor may form a holding to:
-
Hold stakes in multiple startups,
-
Join funding rounds (Series A, B, Seed),
-
Interface with other investors or accelerators.
Advantages:
-
Portfolio consolidation,
-
Tax-free capital gain on sale (if 24-month rule applies),
-
Easier portfolio valuation.
17.2 Venture Holding Structure
A venture capital fund or angel group can use an IKE or S.A. holding to:
-
Participate in startups,
-
Acquire shares in innovation hubs or spinoffs,
-
Join EU funding programs.
18. Common Mistakes in Establishing and Operating a Holding Company
Although the holding structure offers significant advantages, common mistakes in practice can lead to tax penalties, loss of exemptions, or even rejection of the structure by authorities.
18.1 Artificial Setup Without Economic Substance
Establishing a holding without real economic activity (substance), solely to avoid taxes or hide assets, may be classified as:
-
Abuse of rights, or
-
Circumvention of tax provisions,
resulting in denial of exemptions and imposition of penalties or retroactive taxes.
18.2 Lack of Actual Office and Management
The holding must have:
-
A real tax residence (e.g., office, accounts, expenses),
-
A verifiable administrative center (e.g., board meetings, signatures, record-keeping),
-
Bank transactions, payments, and operational expenses.
A company that exists only “on paper” is considered a sham.
18.3 Failure to Meet Deadlines and Legal Requirements
Examples:
-
Dividend distribution without meeting the 24-month holding period,
-
Sale of shares before capital gain exemption conditions are met,
-
Failure to register changes with GEMI (General Commercial Registry).
18.4 Lack of Documentation for Intragroup Transactions
Insufficient documentation of intragroup pricing may lead to tax reassessments.
There must be invoices, contracts, and transfer pricing studies (transfer pricing files).
19. When a Holding Company Does Not Make Sense
Although the holding model is highly useful, there are cases where it is not appropriate, such as:
19.1 Small or Single-Focus Activities
Businesses with only one activity and no participations do not need a holding.
If there is no prospect of sale or succession, the cost of operation may outweigh the benefit.
19.2 High Tax Exposure Without Offsets
If the holding receives dividends without operating expenses or without meeting exemption conditions, it may be taxed normally at 22% + 5%, like any other company.
19.3 Complex and Costly Accounting Management
Holdings with many subsidiaries require specialized accounting monitoring, compliance with Greek Accounting Standards (ELP), and possibly consolidation.
For small businesses, this may not be efficient.
20. Conclusions and Recommended Strategy
The holding company has now become a legally established, operationally flexible, and tax-advantageous tool for modern entrepreneurs, investors, and families planning asset strategy and corporate governance.
Key benefits include:
-
Capital gains and dividend tax exemptions,
-
Legal protection and asset segregation,
-
Investment strategy with tax-free transfers,
-
Financial management and coordination of subsidiaries,
-
Succession and control transfer tool.
However, the success of the structure depends on:
-
The legal accuracy of the articles of association and the corporate structure,
-
Compliance with tax and commercial law,
-
The company’s real operational substance,
-
Guidance from specialized advisors.
Greece now offers a stable, transparent, and internationally accepted regime for holding companies.
A well-designed holding can serve as a pillar of growth, protection, and transition for any modern business structure.